How to Protect Your Legal Rights After a Car Accident
After a crash, you may be managing medical visits, a damaged car and unfamiliar paperwork. Keeping evidence, talking to insurers and preserving your right to file a lawsuit are separate tasks, each with its…
Matt Johnson · Lawyer Monthly
Legal information for general reading, not advice for your situation. Jurisdictions and publication dates vary; consult the original source.
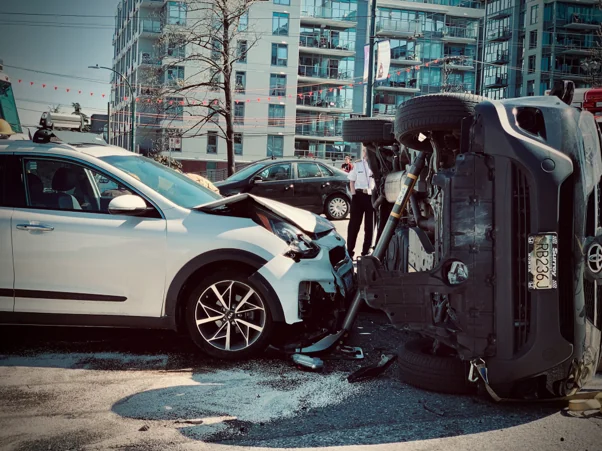
After a crash, you may be managing medical visits, a damaged car and unfamiliar paperwork. Keeping evidence, talking to insurers and preserving your right to file a lawsuit are separate tasks, each with its own requirements. An organized record can help you manage all three.
Key takeaways
- Keep your records together. Witness names, photographs, bills and the crash report are easier to gather now than months later.
- Understand a document before you sign it. A settlement release can end your right to make further claims for the same accident.
- Check deadlines early. Insurance notice, government claim notice and lawsuit filing requirements have separate deadlines.
Protect the evidence while you get care
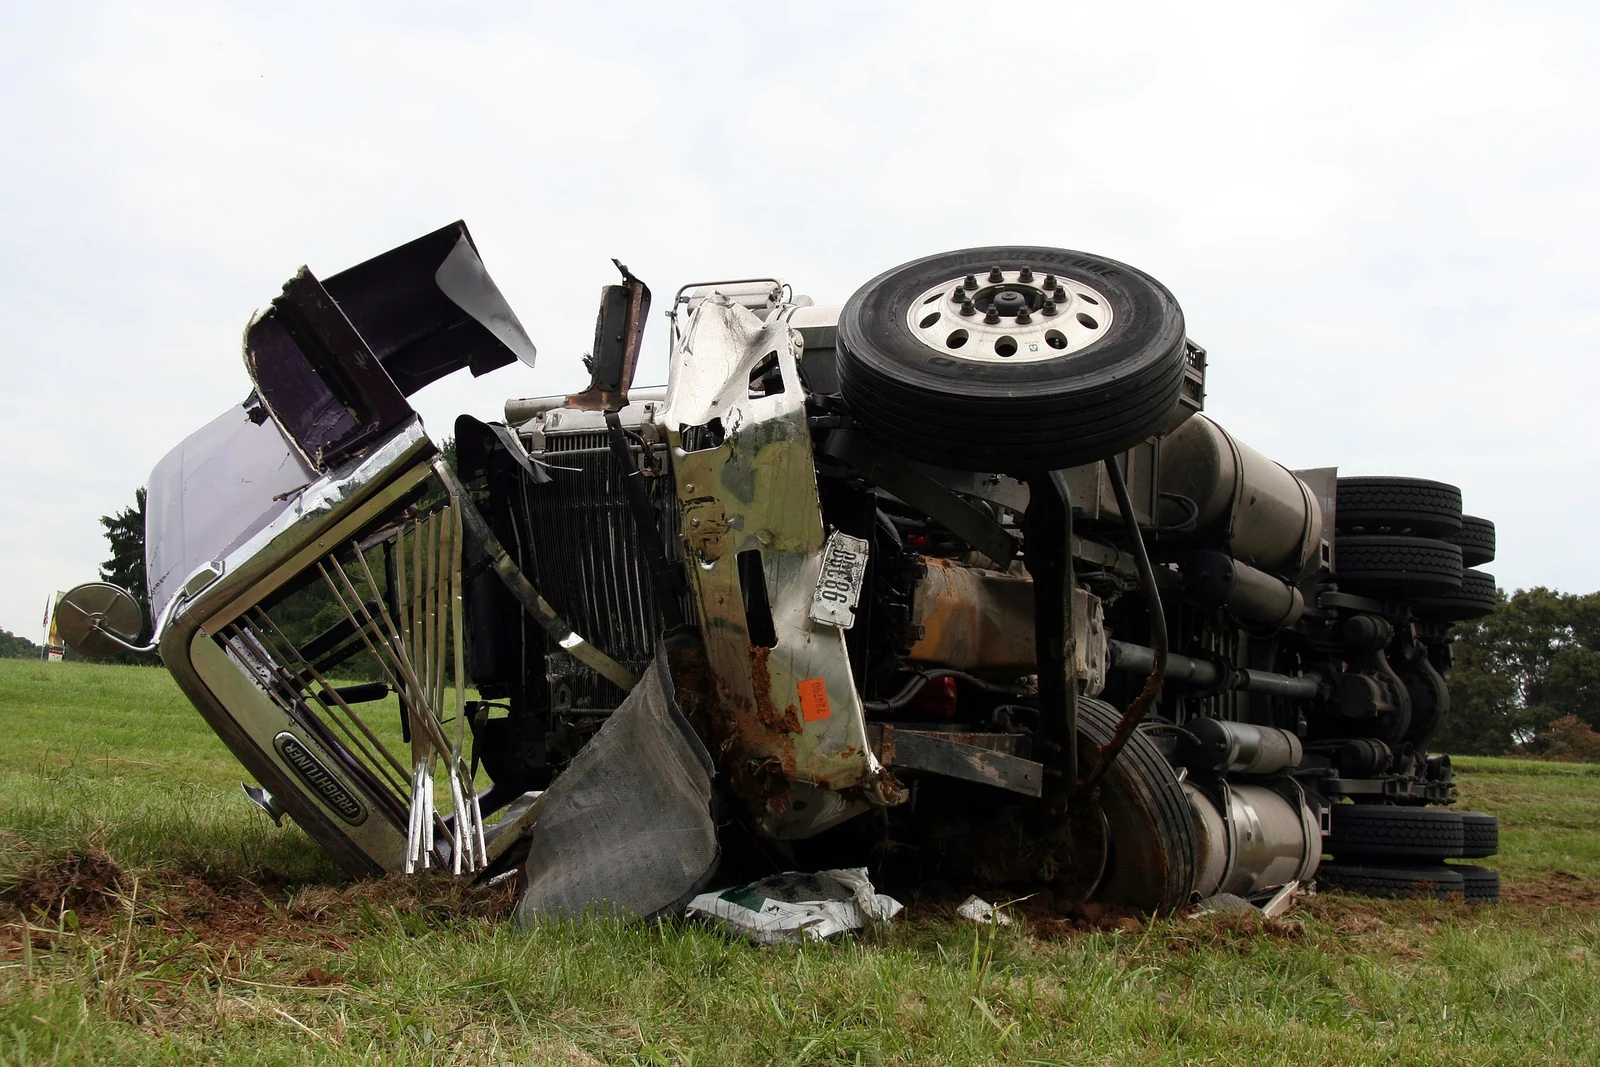
Safety comes first. Move out of traffic if you can do so safely, and check on everyone involved. Under Transportation Code Section 550.026, a driver must notify the appropriate law-enforcement agency immediately when a collision causes injury, death or damage that prevents a vehicle from being driven normally and safely. Never step into a live lane to take photographs.
Get checked by a healthcare provider if you feel hurt or are unsure about symptoms. The CDC's concussion guidance notes that care from a provider can help recovery. Make care decisions based on your health needs, not an assumed claims deadline.
Save what you can. Once you're safe, collect the basics. Well-documented accident claim evidence gives insurers fewer reasons to dispute what happened:
- The other driver's name, driver's license information, license plate number and insurance details
- Photographs of vehicles, the road and any visible injuries, taken from a safe spot
- Witnesses' names and phone numbers, which the Texas Department of Insurance (TDI) recommends collecting
- The police report number
- Medical records, repair estimates, receipts and a record of missed workdays
Keep one organized file. You can buy a copy of the officer's CR-3 crash report through TxDOT's Crash Report Online Purchase System. TxDOT lists a $6 fee for a regular copy, and processing charges may apply. Store it with your other records. Keeping photographs, witness information, reports and financial records together gives later negotiations a reliable factual basis.
Handle insurance conversations carefully
Report the facts. Tell your own insurer about the crash promptly, and check your policy's notice and cooperation requirements. Describe what happened accurately, avoid guessing about speed or distance, and keep a dated log of calls, emails and letters. Keep the report number, bills and insurance messages together so you can refer to them during follow-up conversations.
Understand what is being requested. Your obligations to your own insurer differ from your relationship with the other driver's insurer. TDI cautions that the other company isn't guaranteed to pay, since liability disputes and available coverage can affect the claim. You can ask why a recorded statement or medical authorization is needed before agreeing.
Your own insurer must explain in writing if it denies all or part of your claim. You can also choose the repair shop and parts, though the insurer need not pay more than a reasonable amount. TDI can review complaints about legal or policy violations, but it cannot decide accident fault or make a company pay merely because you disagree with its decision.
Read the release. Before accepting a settlement, find out which claims the release covers. TDI advises talking to your doctor about possible future treatment first, because signing can commit you not to file further claims for the accident. If the wording is unclear, a Houston car accident lawyer can explain which rights you would be giving up. Mostyn Law handles Houston car accident claims on a contingency basis and offers free consultations with no upfront fees.
Understand what can affect your right to recover
Check the filing deadline. Opening an insurance claim is different from filing a lawsuit. Under Civil Practice and Remedies Code Section 16.003, a personal-injury lawsuit generally must be filed within two years after the claim accrues, meaning when it legally arises, subject to exceptions. Don't assume negotiations with an adjuster pause that deadline.
A crash involving a government vehicle or agency can trigger earlier notice requirements. Section 101.101 generally gives a governmental unit the right to receive claim notice within six months of the incident. Houston's claim instructions reproduce a charter requirement for verified written notice within 90 days. These rules, including their applicability and exceptions, need individual review. Seek advice early rather than treating either period as a universal deadline.
Shared fault changes recovery. For claims governed by Texas's proportionate-responsibility rules, Section 33.001 bars recovery if your share of responsibility is greater than 50 percent. If you're otherwise eligible to recover, Section 33.012 reduces your damages by your percentage of responsibility. Document medical expenses, lost income, vehicle damage and ongoing effects on daily life to help explain your losses.
Know when individual advice helps. Disputed fault, a serious injury, a government vehicle or a proposed release are practical reasons to consult a lawyer. Ask how attorney fees and case expenses are handled in the written agreement.
Conclusion
Protecting your rights after a car accident rarely depends on one big decision. It depends on a series of small steps taken early: reporting the crash, getting checked by a provider, saving evidence and keeping every record in one place. Those habits give you a clear account of what happened when insurers start asking questions.
Be just as careful with paperwork and deadlines. Read any release before you sign it, keep a log of every insurance conversation, and note the two-year filing window along with any shorter notice periods that may apply. If fault is disputed, your injuries are serious or a government vehicle was involved, getting individual advice early can help you avoid giving up rights you didn't know you had.
Frequently Asked Questions
How long do I have to file a car accident lawsuit in Texas?
In most cases, a personal-injury lawsuit must be filed within two years after the claim accrues, under Civil Practice and Remedies Code Section 16.003. Some exceptions apply. Talking with an insurance adjuster does not pause this deadline, so opening an insurance claim alone won't protect your right to sue.
What changes if a government vehicle caused the crash?
Claims against a governmental unit can require much earlier notice. Section 101.101 generally gives the governmental unit the right to receive notice within six months of the incident, and Houston's city charter requires verified written notice within 90 days. Because these rules have exceptions, it's worth getting advice as soon as possible.
Can I still recover compensation if I was partly at fault?
Yes, as long as your share of responsibility is not greater than 50 percent. Under Texas's proportionate-responsibility rules, your damages are reduced by your percentage of fault. If you're found more than 50 percent responsible, you can't recover damages under those rules.
Do I have to use the repair shop my insurer recommends?
No. Texas law gives you the right to choose the repair shop and the parts used on your vehicle. The insurer doesn't have to pay more than a reasonable amount for those repairs and parts.
How do I get a copy of my Texas crash report?
You can buy the officer's CR-3 crash report through TxDOT's Crash Report Online Purchase System. TxDOT lists $6 for a regular copy and $8 for a certified copy, which is the version usually needed for legal proceedings. Processing charges may also apply.
Should I sign a settlement release right away?
Not before you understand what it covers. A release can stop you from filing further claims for the same accident. TDI advises talking with your doctor about possible future treatment before you sign, so you know whether the settlement reflects the full cost of your injuries.
Source & rights
Original article: Lawyer Monthly. Original language and source publication date retained.
Article and image rights remain with their original rights holders. This site does not grant blanket reuse permission or claim this source reporting as its own.